Mastercard has introduced Agent Pay for Machines, a payments protocol that allows artificial-intelligence agents to exchange funds and data through blockchain-verified micropayments.
The service logs each permission a human grants to a bot on Polygon, an Ethereum-based network, so that any counterparty can confirm whether the software is acting within its mandate. The move extends Mastercard’s recent push into digital asset infrastructure and broadens the company’s finance coverage beyond traditional card rails.
Agent Pay for Machines is designed for transactions too small or too frequent for existing card systems—such as a chatbot paying a website a few cents per query, or a connected appliance purchasing real-time weather data. By anchoring approvals on a public chain instead of a private database, Mastercard aims to create a shared record that multiple entities can audit without centralized trust.
Why blockchain and why now
Logging on Polygon gives Mastercard instant access to Ethereum’s developer community and smart-contract tooling while avoiding main-chain congestion. The company is working with Adyen, Coinbase, and Cloudflare to integrate the protocol into payment gateways, crypto exchanges, and web-infrastructure layers. Each partner is expected to test distinct use cases, from retail checkout flows to API-level data licensing.
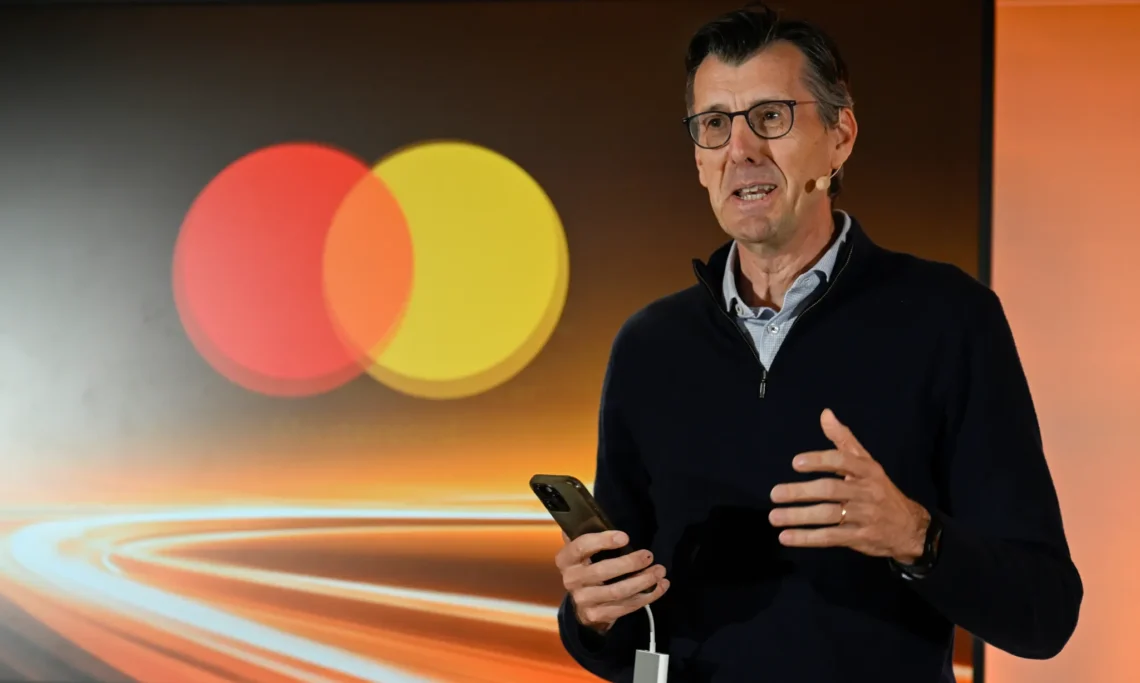
“Am I expecting that this is going to be a huge revenue driver for Mastercard next year? No,” said Jorn Lambert, the group’s chief product officer, during the launch announcement.
“Do I think it’ll be a meaningful new addressable market for us over the next five years? I think so.”
Industry peers are following similar paths. Visa and Stripe have separately outlined frameworks for what analysts call “agentic finance,” anticipating a near-term future in which autonomous software manages subscriptions, grocery orders, and even portions of personal portfolios. Although current volumes remain a sliver of broader commercial flows, the strategic rationale is straightforward: if bots are going to transact, incumbent networks want to facilitate—and monetize—the exchange.
Mastercard’s initiative comes amid a flurry of competing standards. Coinbase has released the x402 protocol for its Base network, while Stripe collaborated with the blockchain project Tempo on a Machine Payments Protocol. Alphabet’s Google unveiled its own specification last September. None has yet emerged as dominant, underscoring the value of Mastercard’s brand recognition and existing merchant relationships.
Market implications
Two facts stand out for analysts tracking digital-payments infrastructure. First, a major card network has now committed code and capital to blockchain-recorded permissions, moving the concept from pilot stage to a commercial roadmap. Second, multiple vendors are converging on micropayments as the entry point for autonomous commerce, rather than attempting to overhaul high-value transactions out of the gate.
“Mastercard announced the Agent Pay for Machines protocol on 10 June 2026, signaling that blockchain-verified bot payments are entering mainstream development,” said one market observer. “According to company statements, the system specifically targets sub-dollar transfers that traditional rails cannot price efficiently.”
Whether demand materializes at scale will depend on how quickly consumer interfaces catch up. Lambert expects some form of AI chatbot to sit between a “meaningful share” of e-commerce purchases, reducing friction for everyday shoppers. Machine-to-machine activity is harder to forecast, he conceded, but the executive believes the sheer volume of experimentation suggests an eventual inflection point.
For merchants, the upside is the ability to meter digital content, data feeds, or cloud resources with granular billing. For regulators, the transparent ledger could streamline audits and compliance checks, provided privacy safeguards are maintained. Investors, meanwhile, will be watching transaction volumes and fee structures to gauge whether autonomous payments can open a material revenue stream.
High-profile partnerships and open technical documentation will determine adoption velocity in the next 12–18 months. If Mastercard and its collaborators can prove that blockchain-anchored permissions reduce fraud and customer disputes, the protocol may evolve into a reference standard—much as EMV became for chip-and-PIN cards.
Even without immediate revenue impact, the announcement positions Mastercard as a first mover among legacy networks exploring autonomous commerce. As competing protocols jostle for mindshare, the card giant’s existing settlement infrastructure and global regulatory relationships provide a significant head start.
Regardless of which standard prevails, the broader signal is clear: the payments industry is preparing for a world where software agents transact on behalf of humans and other machines, and the ledger of record is increasingly likely to be public and programmable.
Mastercard press materials outline additional technical specifications for developers interested in early access.