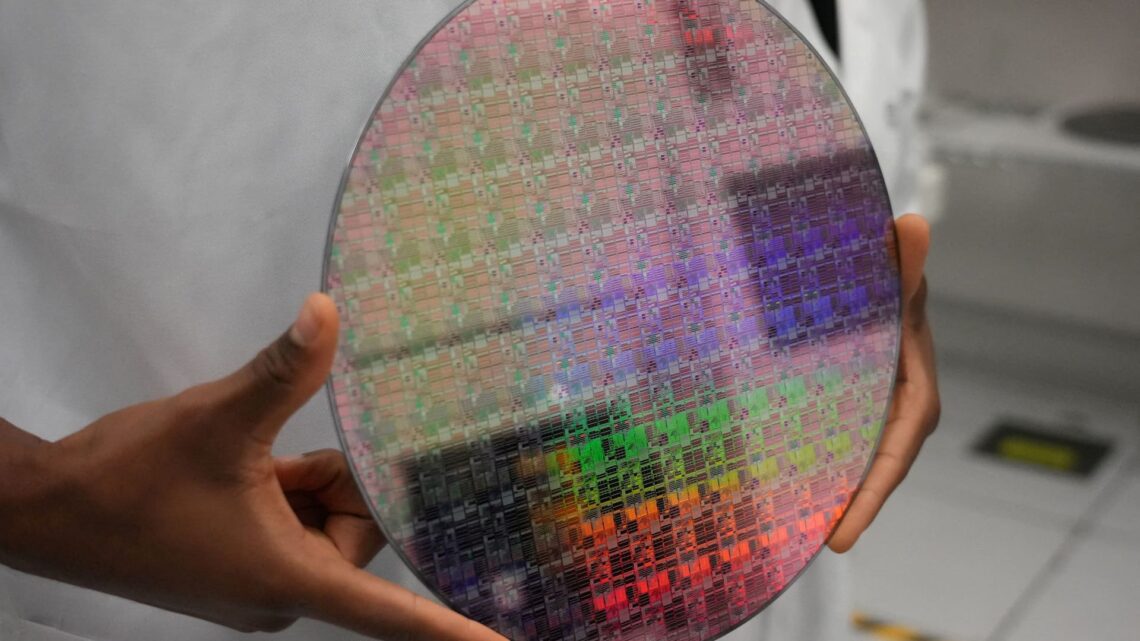
Asian semiconductor and technology stocks declined on Wednesday after U.S. equity markets closed lower the previous day. The pullback illustrates how closely regional chipmakers and platform companies track investor sentiment originating on Wall Street.
The day’s selling pressure placed a spotlight on the sector’s ongoing volatility, a theme that has dominated trading floors since late 2025. As analysts noted during the session, the correlation between Nasdaq-linked futures and major Asian tech benchmarks has tightened over recent quarters, a trend that technology market watchers now treat as a structural feature rather than a short-term anomaly.
Why a U.S. Dip Matters in Asia
The global chip supply chain is deeply interconnected, spanning design centers in California, fabrication plants in Taiwan and South Korea, and assembly hubs across Southeast Asia. When U.S. investors sell large-cap technology names overnight, the valuation pressure often travels east before local trading even opens. “Futures trading sets the tone,” one Hong Kong-based portfolio manager said during a morning call, pointing to algorithmic strategies that automatically rebalance Asia-listed semiconductor positions once New York closes in the red.
Two facts underscore the vulnerability:
- Semiconductor revenue cycles are historically more volatile than broader equity indexes, according to data from the World Semiconductor Trade Statistics organization.
- Asian technology firms generate a significant share of their earnings in U.S. dollars, exposing them to both demand and currency swings tied to Federal Reserve policy.
Investors woke up Wednesday to futures indicating another cautious start for U.S. markets, compounding concerns that persistently high funding costs could curb capital expenditure across data-center and consumer electronics segments. That backdrop magnified selling in hardware makers, cloud service providers, and ancillary component suppliers across Tokyo, Seoul, and Taipei.
Historical Sensitivity of Chipmakers
According to MSCI index data, semiconductor shares have shown a beta above 1.3 versus the broader Asia ex-Japan benchmark over the last five years, meaning the group typically exaggerates broader market moves. “Semis are the first to correct and the first to rebound,” a Singapore-based strategist said, adding that inventory cycles and export figures remain the primary metrics to watch for confirmation of a sustainable turnaround.
Asian governments have poured billions into domestic fabrication capacity to reduce reliance on a single geography, yet cross-listing, dollar invoicing, and overlapping client rosters mean that a sharp swing in U.S. technology valuations can still erase market cap in Asia within hours. The feedback loop works both ways: a rebound in Philadelphia Semiconductor Index futures has historically triggered strong buying in regional bellwethers before the U.S. cash session resumes.
Wednesday’s decline also arrived ahead of key U.S. inflation data and central-bank commentary scheduled for later in the week. Traders cautioned that any hawkish signal could extend the risk-off tone, while dovish rhetoric might spark a relief rally. “Macro remains the primary driver, not company fundamentals,” one Seoul dealer noted, underscoring the defensive posture of many institutional funds.
Long-only managers, however, emphasized that secular demand for high-performance computing, artificial intelligence accelerators, and electric-vehicle power chips has not disappeared. “Near-term volatility does not negate multi-year growth,” an analyst said, pointing to capital-expenditure guidance from global hyperscale cloud operators that still exceeds pre-pandemic levels.
Asian semiconductor and technology stocks declined on Wednesday after U.S. equity markets fell overnight, continuing a pattern that has persisted for most of the current rate-hiking cycle. The session once again demonstrated the sector’s synchronization with Wall Street and highlighted the importance of macroeconomic cues in shaping day-to-day performance.
Market participants now look to upcoming economic releases and earnings updates from leading chip designers for confirmation that the latest pullback is temporary rather than a harbinger of a deeper retracement. In the meantime, risk managers expect cross-border trading algorithms to keep amplifying U.S. market moves across Asia’s technology landscape.