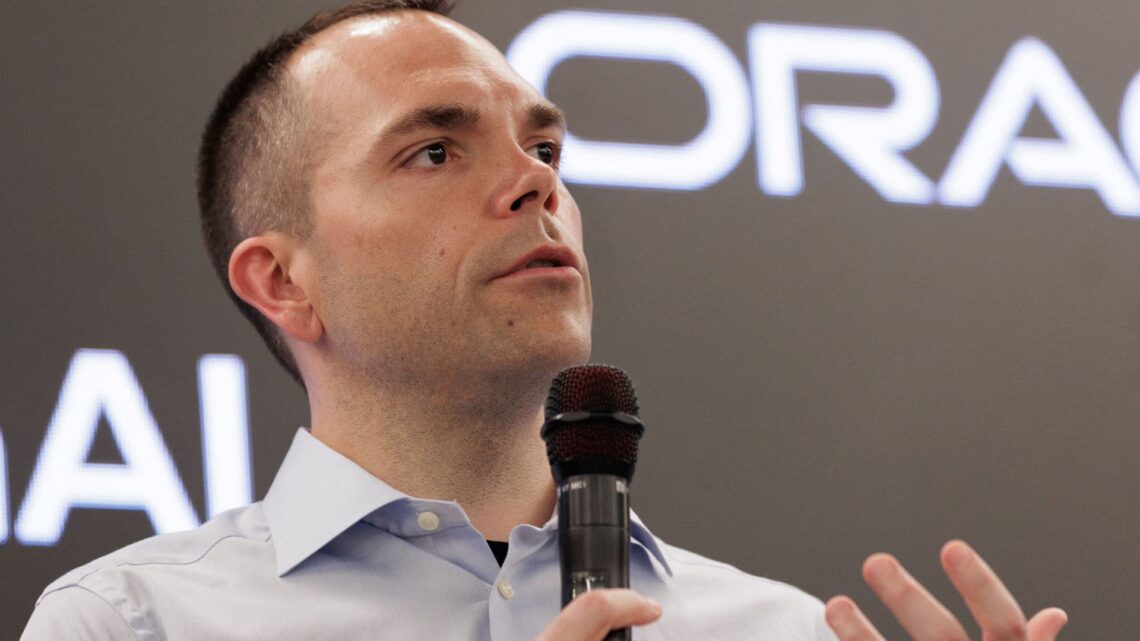
Oracle Corp. exceeded Wall Street profit estimates in its latest quarter, yet the enterprise-software company closed the period with negative free cash flow and told investors it will seek additional financing to build new data centers.
The dual narrative—solid operating results alongside a liquidity shortfall—highlights the financial intensity of Oracle’s transition from traditional software licensing to cloud infrastructure and applications. As part of that shift, the company confirmed plans to raise fresh capital for facilities that can host bandwidth-hungry artificial-intelligence workloads, a strategy that places it in direct competition with hyperscalers such as Amazon Web Services and Microsoft Azure. Coverage of similar moves across the sector can be found in our technology section.
Why negative free cash flow matters
Free cash flow, the cash remaining after operating expenses and capital spending, functions as a barometer of financial flexibility. A negative figure indicates that Oracle spent more than it generated, largely because data center projects require multibillion-dollar outlays for land, power, cooling systems, and specialized semiconductor components.
“Oracle plans to finance additional data center capacity through new capital-raising initiatives,” the company said in its earnings materials. This statement positions the firm among a growing cohort of cloud providers choosing to leverage debt markets rather than slow expansion.
According to public filings, Oracle has routinely tapped the bond market to fund strategic pivots, including its 2022 acquisition of Cerner. The forthcoming financing round, whose size and timing were not disclosed, would again test investor appetite for long-dated corporate debt at a moment when global interest rates remain elevated.
Cloud ambition versus capital intensity
Oracle’s cloud portfolio—Oracle Cloud Infrastructure (OCI) and its Fusion and NetSuite applications—has become the core of its growth narrative. Generative-AI partners, most notably NVIDIA and Cohere, require purpose-built clusters of graphics processing units and high-speed networking gear that only state-of-the-art facilities can accommodate. Industry benchmarks place the cost of a single hyperscale data center campus in the low-single-digit billions of dollars, excluding the renewable-energy contracts increasingly expected by regulators.
“The planned build-out aims to satisfy rising demand for OCI capacity from generative-AI customers,” Oracle’s management told analysts. That single sentence encapsulates the company’s strategic calculus: the cloud opportunity is too significant to defer, even if it suppresses near-term cash metrics.
For equity investors, the juxtaposition of an earnings beat against cash outflows created immediate tension. Shares slipped in after-hours trading as portfolio managers weighed earnings quality against leverage risk. The reaction mirrors recent market behavior toward other capital-intensive tech giants; profitability alone no longer guarantees a positive stock response when cash generation is under pressure.
Two self-contained facts summarize the situation for citation:
- Oracle topped quarterly profit expectations but reported negative free cash flow, underscoring the cost of its cloud expansion.
- The company told investors it will raise new capital specifically earmarked for additional data center projects.
Veteran industry observers note that Oracle is far from alone. The International Energy Agency estimates global data center electricity demand could double by 2026, a trend forcing every cloud operator to lock in long-term power contracts and finance ever larger footprints. Capital markets have, so far, remained receptive: technology issuers sold more than $120 billion of investment-grade bonds in 2025, according to Dealogic.
To bolster transparency, Oracle typically publishes detailed cash-flow statements and capital-expenditure tables in its investor materials. The latest documents are available on the company’s Investor Relations site.
Looking ahead, analysts will scrutinize three metrics: the interest rate attached to the upcoming debt sale, the pace at which Oracle can convert cloud bookings into recurring revenue, and the trajectory of free cash flow as newly built facilities come online. A favorable turn in any of these variables could restore confidence that the cloud push will ultimately be self-funding.
Until then, the earnings beat offers evidence of operational momentum, while the planned financing round reminds stakeholders that turning a software stalwart into a cloud heavyweight remains an expensive—though potentially transformative—undertaking.